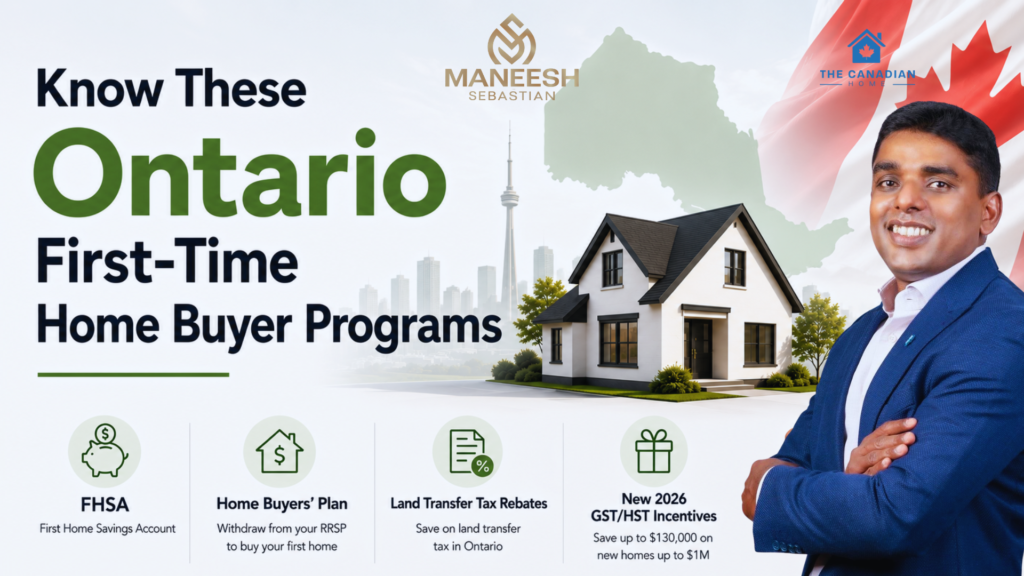
Did you know you could save thousands of dollars through Ontario’s first-time home buyer programs?
From the FHSA and Home Buyers’ Plan to Land Transfer Tax rebates and new 2026 GST/HST incentives, several programs can help eligible buyers reduce the cost of purchasing a home.
Whether you’re looking for a condo in Toronto, a townhouse in Mississauga or Burlington, or a new home in Milton, Hamilton, Cambridge, or Guelph, this guide breaks down the key first-time home buyer programs, rebates, and tax benefits in Ontario and what you need to know before making an offer.
Planning your first purchase? Start with our First-Time Home Buyer Guide in the GTA to understand the complete buying process, from mortgage pre-approval to closing.
1. First Home Savings Account (FHSA)
Could an FHSA help you build your first-home savings while reducing your taxable income?
The First Home Savings Account (FHSA) is a registered savings plan designed to help eligible Canadians save for their first home.
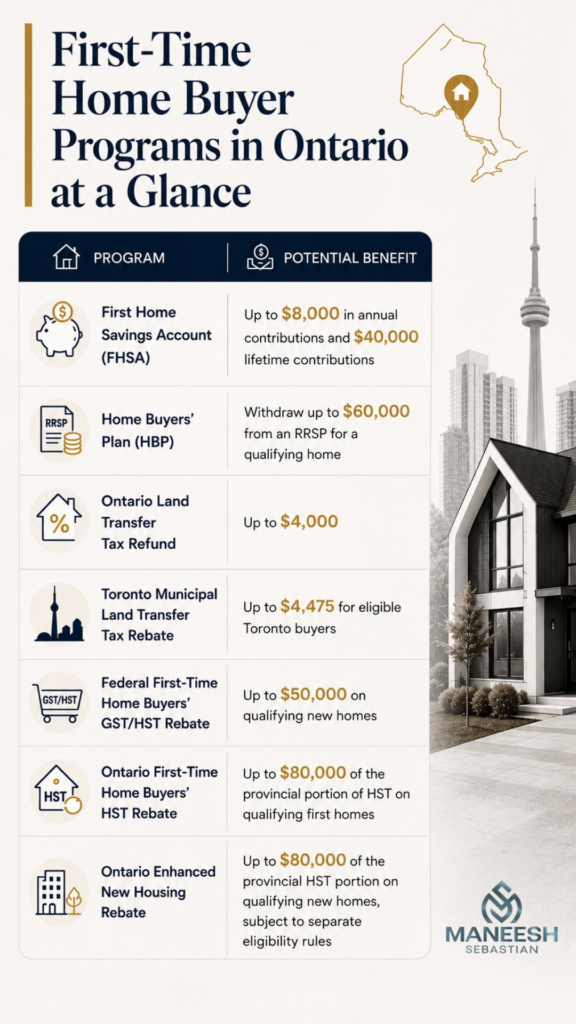
You receive $8,000 of FHSA participation room in the first year you open an FHSA, with a lifetime contribution limit of $40,000. Unused participation room can be carried forward, subject to the FHSA rules and an $8,000 maximum carry-forward amount.
Eligible FHSA contributions can generally be deducted from your taxable income. When you make a qualifying withdrawal to purchase a qualifying first home, the withdrawal can be made tax-free.
Why the FHSA Can Help
- Save for your first home with a dedicated registered account
- Reduce taxable income through eligible contributions
- Make qualifying tax-free withdrawals for your home purchase
- Build your down payment with tax-advantaged savings
If you’re planning to buy your first home in the next few years, opening an FHSA early can give you more time to build a contribution room and savings. Keep in mind that carry-forward room only begins accumulating once you open your first FHSA.
Can You Use an FHSA With the Home Buyers’ Plan?
Yes. If you meet the eligibility requirements for both programs, you can use your FHSA and Home Buyers’ Plan for the same qualifying home.
2. Home Buyers’ Plan (HBP)
Did you know you may be able to use up to $60,000 from your RRSP toward your first home?
The Home Buyers’ Plan (HBP) allows eligible individuals to withdraw up to $60,000 from their RRSP to buy or build a qualifying home without paying tax on the withdrawal at the time it is made. If two eligible buyers purchase a home together, each may be able to withdraw up to $60,000 from their own RRSP.
How the HBP Can Help
- Increase your down payment using eligible RRSP savings
- Reduce the amount you need to borrow
- Potentially lower your mortgage amount
- Use the HBP alongside an FHSA for the same qualifying home, if you meet the requirements for both programs
Important HBP Repayment Rule
HBP withdrawals must generally be repaid to your RRSP over a period of up to 15 years. Under the standard rule, repayment begins in the second year after the year of your first withdrawal.
There is currently a temporary repayment deferral for participants whose first HBP withdrawal was made between January 1, 2022 and December 31, 2025. For these participants, the 15-year repayment period begins in the fifth year following the year of the first withdrawal.
| NOTE:The federal government’s 2026 Economic Update proposes extending this five-year repayment relief to first withdrawals made through the end of 2028, but this should be treated as a proposed change until officially enacted. |
HBP and FHSA Can Work Together
If you’re eligible for both programs, you can use your FHSA and HBP for the same qualifying home. This can give you more flexibility when planning your down payment.
3. Ontario Land Transfer Tax Refund
Buying a home comes with more than just the purchase price. Land Transfer Tax is one of the costs you’ll need to account for at closing, but eligible first-time buyers in Ontario can receive a refund of up to $4,000.
The refund can cover the Land Transfer Tax payable on the first $368,000 of the home’s purchase price. If the property costs more than $368,000, the maximum refund remains $4,000. (ontario.ca)
Who May Qualify?
You generally need to:
- Be 18 years or older
- Have never owned an eligible home or an interest in one anywhere in the world
- Have a spouse who has not owned an eligible home while being your spouse
- Be a Canadian citizen or permanent resident, subject to Ontario’s rules
- Occupy the property as your principal residence within nine months of the transfer (ontario.ca)
How Do You Claim the Refund?
The refund can generally be claimed when the property is registered, allowing it to reduce the Land Transfer Tax payable at closing. If you don’t claim it at registration, you can apply to the Ontario Ministry of Finance afterward, generally within 18 months of the registration or disposition. (ontario.ca)
Buying in Toronto? You may also qualify for a separate Toronto Municipal Land Transfer Tax Rebate, which can provide additional savings for eligible first-time buyers.
4. Toronto Municipal Land Transfer Tax Rebate
When you buy a property in Toronto, you pay Municipal Land Transfer Tax (MLTT) to the City in addition to Ontario’s provincial Land Transfer Tax. The tax is based on the property’s purchase price and is typically paid when ownership is transferred.
The good news is that eligible first-time home buyers can receive a rebate of up to $4,475 on the Toronto MLTT.
What Could You Save?
If you qualify for both rebates:
- Ontario Land Transfer Tax Refund: Up to $4,000
- Toronto MLTT Rebate: Up to $4,475
- Potential combined relief: Up to $8,475
These rebates are subject to the eligibility requirements and the amount of tax payable.
Buying in Toronto? Make sure you check both provincial and municipal rebates before budgeting for your closing costs.
5. Federal First-Time Home Buyers’ GST/HST Rebate
Buying a new home can mean paying GST or the federal portion of HST on top of the purchase price. The new federal First-Time Home Buyers’ GST/HST Rebate helps eligible first-time buyers recover some or all of that tax on a qualifying new or substantially renovated home.
How Much Could You Get?
- $1 million or less: Up to $50,000
- $1 million to under $1.5 million: Rebate gradually decreases
- $1.5 million or more: No federal rebate
The rebate can apply to qualifying newly built or substantially renovated homes, including certain homes purchased from builders and eligible owner-built homes. The property must meet the program requirements, including being intended as your primary residence.
For GTA buyers considering a new condo, townhouse, or detached home, this rebate could make a meaningful difference to your upfront costs.
6. Ontario First-Time Home Buyers’ HST Rebate
For eligible first-time buyers purchasing a qualifying new home in Ontario, the provincial portion of HST can represent a significant upfront cost. Ontario’s first-time home buyer rebate can help eligible buyers recover up to $80,000 of the provincial portion of HST.
The rebate applies to qualifying new or substantially renovated homes and is subject to specific eligibility requirements. The $80,000 is the maximum, not a guaranteed payment for every buyer.
What Does the $80,000 Mean?
- Up to $1 million: Up to $80,000
- $1 million to $1.5 million: The rebate can still be up to $80,000, subject to the applicable HST and program rules
- Eligibility depends on the buyer, property, and transaction requirements.
For GTA buyers considering a new condo, townhouse, or detached home, this rebate can be an important part of calculating the true cost of a new-build purchase.
| NOTE: Don’t confuse this with the Ontario Enhanced New Housing Rebate, which is a separate temporary measure. The ENHR can also provide up to $80,000 of the provincial HST portion on qualifying new or substantially renovated homes, generally for builder agreements entered into between April 1, 2026 and March 31, 2027. |
7. Ontario Enhanced New Housing Rebate
Buying a new or substantially renovated home in Ontario may qualify you for additional relief on the provincial portion of HST. The Ontario Enhanced New Housing Rebate (ENHR) can provide eligible buyers with up to $80,000 of the provincial 8% HST portion.
The temporary rebate generally applies to builder agreements entered into between April 1, 2026 and March 31, 2027, subject to the program’s eligibility requirements.
How Much Could You Receive?
- Up to $1 million: Up to $80,000
- $1 million to $1.5 million: $80,000
- $1.5 million to $1.85 million: Partial rebate
- $1.85 million and above: The enhanced rebate is not available, but the existing Ontario new housing rebate may provide up to $24,000.
Is the ENHR Only for First-Time Buyers?
No. The Ontario ENHR is not exclusively a first-time home buyer program. Eligible buyers who meet the program’s requirements may qualify even if they have owned a home before.
However, if you are a first-time buyer, the ENHR can interact with Ontario’s separate First-Time Home Buyers’ rebate. Eligible buyers may be able to claim either or both Ontario rebates, but the total rebates for the 8% provincial HST portion cannot exceed the lesser of $80,000 or the provincial HST payable on the purchase.
For GTA buyers: If you’re considering a new condo, townhouse, or detached home, check which HST rebates apply before signing your purchase agreement, as eligibility depends on the property, purchase price, agreement date, and other conditions.
Can You Combine First-Time Home Buyer Programs?
Yes, you may be able to use multiple programs for the same home, provided you meet the eligibility requirements for each.
Depending on your situation, you may be able to combine:
- FHSA
- Home Buyers’ Plan
- Ontario Land Transfer Tax Refund
- Toronto Municipal Land Transfer Tax Rebate
- Federal First-Time Home Buyers’ GST/HST Rebate
- Ontario First-Time Home Buyers’ rebate
However, don’t simply add the maximum amounts together. Each program has its own eligibility rules, limits, and conditions.
For new homes, the Ontario HST rebates also have specific rules about how they interact, so your actual savings will depend on the property, purchase price, and transaction.
So, check which programs apply to your specific purchase before making an offer.
| Who Qualifies as a First-Time Home Buyer?There is no single definition that applies to every first-time home buyer program. Eligibility can vary depending on the incentive, your previous home ownership, the property, and other requirements.For example, the federal First-Time Home Buyers’ GST/HST Rebate has its own eligibility rules, including requirements related to age, residency, and previous home ownership. (canada.ca)So, qualifying as a first-time buyer for one program does not automatically mean you qualify for every program. |
Other Costs First-Time Buyers Should Budget For
Government programs can reduce some costs, but they don’t eliminate the overall expenses of homeownership.
Your budget may also need to include:
- Down payment
- Land Transfer Tax
- Legal fees
- Home inspection
- Title insurance
- Mortgage-related expenses
- Property taxes
- Home insurance
- Moving costs
- Utility setup
- Repairs and maintenance
- Furniture and appliances
- Emergency savings
A strong home-buying plan should leave you with enough financial room after closing, not just enough money to complete the purchase.
What Should You Do Before Buying Your First Home?
A simple five-step approach can help.
1. Review Your Finances
Look at your income, savings, debts, credit profile, and monthly expenses.
2. Check First-Time Buyer Programs
Find out whether you may qualify for the FHSA, HBP, Land Transfer Tax rebates, or new GST/HST incentives.
3. Get Mortgage Pre-Approved
Understand your potential purchasing power before you start viewing homes.
4. Set Your Total Budget
Include the purchase price, closing costs, taxes, moving expenses, and ongoing homeownership costs.
5. Start Exploring GTA Neighbourhoods
Compare communities such as Toronto, Mississauga, Milton, Oakville, Burlington, Hamilton, Cambridge, Guelph, and Kitchener-Waterloo based on your budget and lifestyle.
Not sure where to start? Explore our guide to the 9 Best GTA Cities for First-Time Home Buyers to compare different communities and find the right fit.
Let’s Find the Right Home for You
Tell me what you’re looking for, and I’ll help you explore the right GTA homes and neighbourhoods for your budget and goals.
Contact me, Maneesh Sebastian, for a free consultation and let’s start planning your first home purchase.